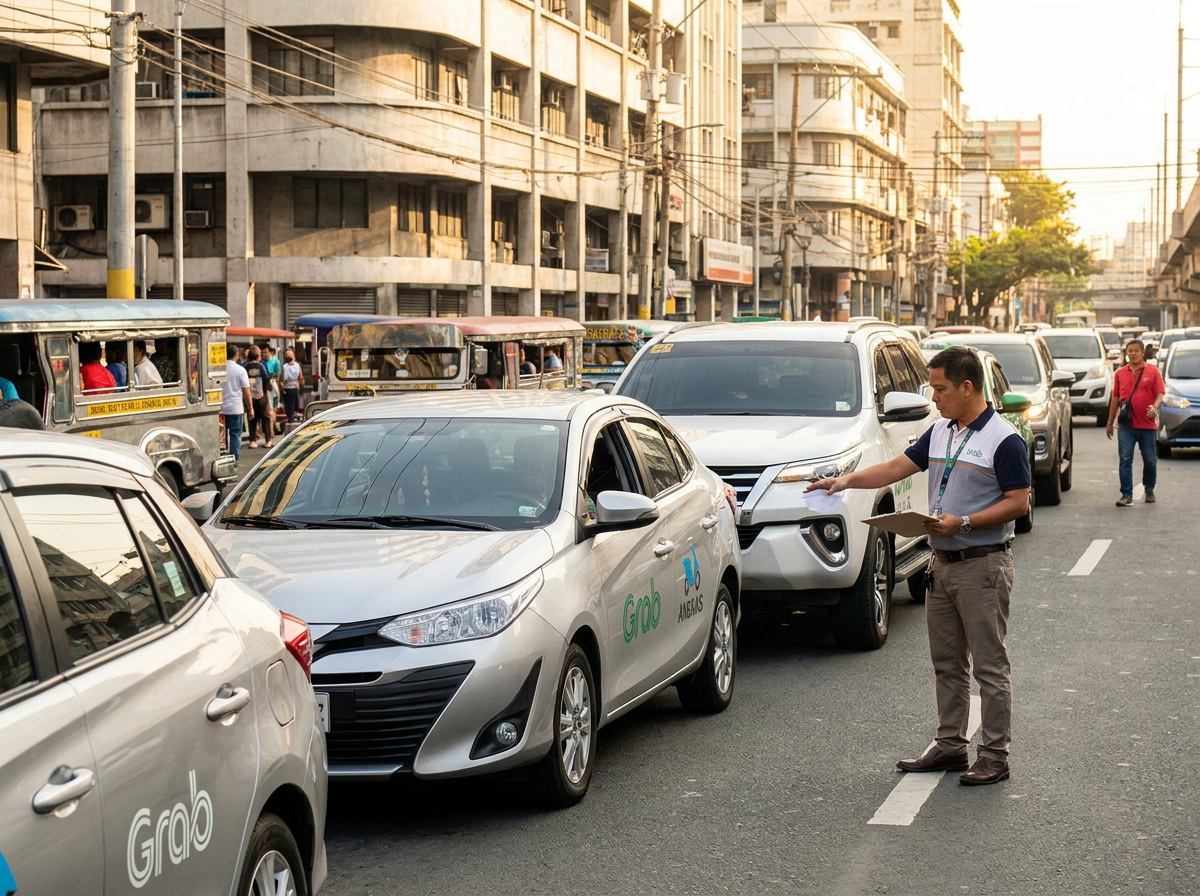
Running a single TNVS vehicle for Grab or another LTFRB-accredited platform is already a business operation. Running two, five, or twenty? That is a fleet — and fleet operations come with a distinct set of insurance requirements, compliance obligations, and risk management considerations that single-vehicle operators never encounter.
In the Philippines, the ride-hailing industry has grown significantly over the past decade. Beyond individual drivers earning supplemental income, a new class of TNVS entrepreneurs has emerged: fleet operators who own and manage multiple accredited TNVS vehicles, hire professional drivers, and run their units as a formal transportation business.
If you are managing a TNVS fleet — or considering expanding from a single vehicle to multiple units — this guide covers everything you need to know about fleet insurance structure, LTFRB compliance, and how to manage your insurance program efficiently across multiple vehicles.
What Makes TNVS Fleet Insurance Different?
Individual TNVS operators typically purchase a separate insurance policy for each vehicle. That approach is straightforward when you have one car — but when you own five, ten, or twenty TNVS units, managing individual policies creates real operational complexity: different renewal dates, multiple insurer relationships, fragmented claims tracking, and inconsistent coverage terms across your fleet.
Fleet insurance, by contrast, covers multiple vehicles under a single policy framework or master agreement. For TNVS operators with more than one vehicle, the core benefits are significant:
- Unified renewal management — all vehicles renew under the same schedule, eliminating the risk of lapses caused by overlooked individual renewal dates
- Volume-based premium advantages — fleet policies often yield better rates per vehicle than purchasing individual policies, because the insurer spreads risk across a larger vehicle pool
- Consistent coverage terms — all vehicles carry identical coverage structure, so your risk management is standardized and predictable
- Simplified claims administration — a single point of contact for all claims across the fleet, rather than managing multiple insurer relationships
Not all insurance providers offer fleet products for TNVS vehicles in the Philippines, and those that do structure their fleet programs differently. This is one area where working with an independent insurance agency — one that can access and compare fleet products across multiple Insurance Commission-accredited insurers — provides a real competitive advantage to fleet operators.
LTFRB Compliance for TNVS Fleet Operators
LTFRB compliance does not change fundamentally because you operate multiple vehicles — each vehicle must still carry valid insurance as a condition of its individual Certificate of Public Convenience (CPC). What changes is the operational burden of managing that compliance across a fleet of vehicles simultaneously.
Key compliance considerations for TNVS fleet operators include:
Individual Certificates of Cover per Vehicle
Even under a fleet insurance program, each TNVS unit must have its own Certificate of Cover (COC) confirming active coverage. This document is required for LTFRB franchise renewal and LTO registration purposes. Confirm with your insurer or insurance advisor that individual COCs are issued for every covered vehicle in your fleet, even when they fall under a single master policy.
Driver Change Notifications
TNVS fleet operators frequently have multiple drivers operating the same vehicle across shifts. Some fleet policies require notification when a principal driver changes, or include restrictions on the number of named drivers per vehicle. Review your policy's driver clauses carefully to ensure all operators across your fleet are covered — an unnamed driver involved in an accident may trigger a policy exclusion.
Timely Endorsement of New Vehicles
When you add a new vehicle to your fleet, it must be endorsed onto the insurance program before the vehicle begins operating as a TNVS unit. Operating an unendorsed vehicle under a fleet policy typically means that vehicle has no valid coverage — despite your broader fleet policy being active. This is a common compliance gap that can have serious financial consequences if an accident occurs.
Fleet operator caution: Fleet expansion periods are the highest-risk times for coverage gaps. Establish a formal internal procedure — notify your insurance advisor before any new vehicle is deployed, not after. A single unendorsed vehicle in operation represents significant uninsured liability exposure for your entire business.
Managing Risk Across a TNVS Fleet
When you operate a fleet, your risk profile is fundamentally different from an individual TNVS operator. Fleet-specific exposures include:
- Multiple simultaneous incidents — if two of your vehicles are involved in separate accidents on the same day, you face parallel claims processing and potential simultaneous deductible payments
- Driver quality variability — individual drivers' experience levels, habits, and accident histories contribute directly to your fleet's overall claims frequency and future premium rates
- Vehicle concentration risk — if your fleet is parked at a common overnight location, a single flooding event, fire, or theft incident could affect multiple units simultaneously
- Operational continuity risk — a major incident affecting several vehicles at once can disrupt income generation across your entire fleet, not just one unit
Effective risk management for TNVS fleet operators goes beyond simply having insurance in place. Practical measures that reduce claims exposure include:
- Maintaining written driver records and screening new drivers before adding them to your fleet operations
- Implementing consistent vehicle maintenance schedules with service records kept on file, to reduce mechanical failure risk and support claims documentation
- Dispersing vehicle storage across locations where practical, to reduce concentration risk during typhoon season and flooding events
- Establishing clear internal incident reporting protocols so all claims are reported to your insurer promptly and accurately — delayed reporting is one of the most common causes of claim complications
An insurance advisor experienced in fleet operations can help you structure coverage that addresses these specific exposures, rather than simply applying a standard single-vehicle TNVS template across multiple units.
How to Get the Right Fleet Insurance for Your TNVS Business
Whether your fleet currently has two vehicles or twenty, securing the right coverage requires a structured approach. Here is what experienced TNVS fleet operators do before purchasing or renewing their fleet insurance program:
1. Inventory Your Fleet Accurately
List all vehicles by make, model, year, LTO plate number, and LTFRB CPC number. Insurers require complete, accurate vehicle information to quote fleet policies correctly. Errors or omissions in your fleet inventory can result in coverage gaps or disputed claims.
2. Compile Your Claims History
If your vehicles have prior claims under individual policies, gather those records. Insurers use claims history to assess risk and price fleet coverage. A clean claims history typically results in more favorable terms; a history with frequent claims will be priced accordingly.
3. Clarify Your Driver Arrangements
Determine whether each vehicle has a single principal driver, multiple shift-based drivers, or a rotating driver pool. Your policy structure must accommodate how your fleet actually operates. Misrepresenting driver arrangements — even unintentionally — can give an insurer grounds to limit a claim.
4. Work With an Independent Insurance Agency
Not all insurers write fleet TNVS business in the Philippines, and those that do offer varying terms, deductible structures, and per-vehicle premium rates. An independent agency can identify which providers are most competitive for your specific fleet profile and bring you multiple options to compare — rather than presenting a single take-it-or-leave-it offer from one company.
5. Schedule Annual Policy Reviews
Fleet compositions change: vehicles are added, retired, or replaced; drivers change; operations may expand into new areas. Annual policy reviews ensure your coverage always reflects your current fleet rather than the fleet you had when you first purchased the policy. Coverage that was appropriate for a five-vehicle fleet may need restructuring when the fleet grows to fifteen.
A note on deductibles: Fleet policies sometimes carry higher per-incident deductibles in exchange for lower per-vehicle premiums. Before accepting a fleet policy on premium alone, calculate whether the deductible structure makes practical sense for your fleet size. A lower premium that comes with a very high deductible may cost more overall when you account for the claims you are likely to actually file across an active TNVS fleet.
Building a Sustainable TNVS Fleet Business Starts With the Right Foundation
A TNVS fleet is a real business investment — in vehicles, in drivers, and in the operational infrastructure that keeps multiple units moving and earning every day. Like any serious business investment, it requires serious risk management.
Fleet insurance is not simply scaled-up individual insurance. It is a different product category that, when structured correctly, provides fleet operators with better coverage management, potential premium efficiencies, and a cleaner compliance profile with the LTFRB — all of which contribute directly to the profitability and sustainability of the fleet business.
If you are currently managing a TNVS fleet with individual policies for each vehicle, or if you are considering expanding your fleet and want to understand your insurance options, speaking with an independent insurance advisor is the right starting point. The right fleet insurance structure protects your vehicles, your drivers, your passengers, your LTFRB compliance, and ultimately, the income your fleet generates every day.
Get a Free Quote Today
Ready to protect what matters most? Our insurance experts are here to help you find the right coverage at the best price. OneNetworx Insurance Agency is an independent, non-tied agency — we compare TNVS fleet insurance options from multiple top Philippine insurers so you get unbiased guidance, not a single-company pitch.
🌐 www.onenetworxinsurance.com
About the Author
Angelo Villamejor is a former financial wealth branch manager at a top Philippine life insurance company and a GAMA Awardee, with nearly three decades of experience spanning insurance brokerage, bancassurance, non-life and life insurance leadership. He leads OneNetworx Insurance Agency with a focus on giving Filipino families and businesses unbiased, expert guidance to find coverage that holds up when it matters most.